Search results for income tax e-filing in India 2026 2026 2026 2026 2026
- incometax.gov.in › iec › foportal › helpEN
Income Tax Returns
# Income Tax Returns ## [Income Tax Returns FAQs](https://www.incometax.gov.in/iec/foportal/help/all-topics/e-filing-services/%20income%20tax%20returns-faq) ### 4. Under which Act will the ITR for income earned during FY 2025 -26 be filed? Even though the filing will typically occur after 1st April, 2026 (i.e., after the new Act has come into force), the return relates to a tax year beginning before 1st April, 2026 and is therefore governed entirely by the old Act. ### 5. Which ITR form should be used for AY 2026 -27? For AY 2026 -27, the ITR forms (ITR -1, ITR -2, ITR -3, ITR -4, ITR -5, ITR -6, ITR -7) applicable under the Income Tax Act, 1961 will soon be notified. These forms will be available on the e -filing portal well before the due date. ### 8. Can a taxpayer file an updated return (ITR -U) for AY 2026 -27 under the old Act after the new Act comes into force? Yes. The updated return for AY 2026 -27 under Section 139(8A) of the old Act can be filed within the time period prescribed therein, even after the new Act has come into force. The old Act continues to govern all proceedings relating to tax years before 1st April, 2026. X filed his original ITR for AY 2026 -27 on 25th July, 2026. He can file an updated return (ITR -U) for AY 2026 -27 under the old Act, subject to the time limits and additional tax requirem ents prescribed in Section 139(8A) of the old Act. ### 16. Are AY 2026 -27 and Tax Year 2026 -27 the same? These are two entirely separate compliance obligations: The due date is 31st July, 2026 or 31st August for non -audit cases , etc. (ii) For Tax Year 2026 -27 (income of FY 2026 -27): This return is not due until July 2027. However, the taxpayer should keep track of income, TDS, and advance tax payments under the new Act framework from April 2026 onwards. The e -filing portal will support compliances under both the Acts simultaneously. ### 24. The tax audit report for FY 2025 -26 will be filed after 1st April, 2026. Which Act will govern the filing of the tax audit report for FY 2025 -26 (AY2026 -27)? 2026 . ### 26. Will the e -filing portal simultaneously supports filings under both the old and new Acts? Yes. ### 27. How should taxpayers keep records for the transition year to ensure smooth filing under both Acts? Last reviewed and updated on : 06-Nov-2026
- incometax.gov.in › iec › foportalEN
Income Tax Department: Home
[](https://www.incometax.gov.in/iec/foportal/) # [](https://www.incometax.gov.in/iec/foportal/) Home | Income Tax Department Form 3 under the “Foreign Assets of Small Taxpayers Disclosure Scheme” is now available for online filing Due dates for filing of Income Tax Returns and Audit Reports for AY 2026-27 are extended in the cases of persons mentioned at Sl.No.2 in the Table below Explanation2 to Sub-section (1) of Section 139 of Income Tax Act 1961 vide Circular No.07/2026 dated 28th September,2026. 3. Form 1 under the “Foreign Assets of Small Taxpayers Disclosure Scheme” is now available for filing. ITR-1, ITR-2, ITR-3, ITR-4, ITR-5, ITR-6 and ITR-7 for AY 2026-27 are available for filing through both online and offline utilities. Filing of TDS/TCS Correction Statements pertaining to Tax Year 2026-27 has been enabled. DFC may be contacted through the e-mail id: [taxdemand@cpc.incometax.gov.in](mailto:taxdemand@cpc.incometax.gov.in) or on the toll-free number - 1800 309 0131 or chargeable no. 0821-6671200. Excel utilities for filing Updated return for ITR-1 to 7 for AY 2022-23 as per Finance Act, 2026 are available for filing ! Form 3 under the “Foreign Assets of Small Taxpayers Disclosure Scheme” is now available for online filing Due dates for filing of Income Tax Returns and Audit Reports for AY 2026-27 are extended in the cases of persons mentioned at Sl.No.2 in the Table below Explanation2 to Sub-section (1) of Section 139 of Income Tax Act 1961 vide Circular No.07/2026 dated 28th September,2026. 3. Form 1 under the “Foreign Assets of Small Taxpayers Disclosure Scheme” is now available for filing. ITR-1, ITR-2, ITR-3, ITR-4, ITR-5, ITR-6 and ITR-7 for AY 2026-27 are available for filing through both online and offline utilities. Filing of TDS/TCS Correction Statements pertaining to Tax Year 2026-27 has been enabled. DFC may be contacted through the e-mail id: [taxdemand@cpc.incometax.gov.in](mailto:taxdemand@cpc.incometax.gov.in) or on the toll-free number - 1800 309 0131 or chargeable no. 0821-6671200. Excel utilities for filing Updated return for ITR-1 to 7 for AY 2022-23 as per Finance Act, 2026 are available for filing ! 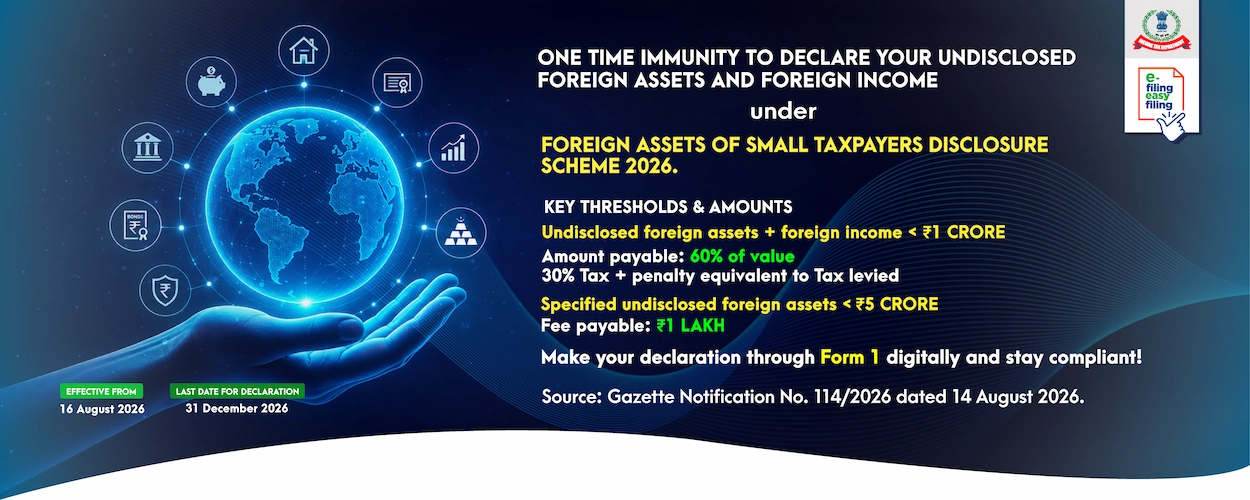 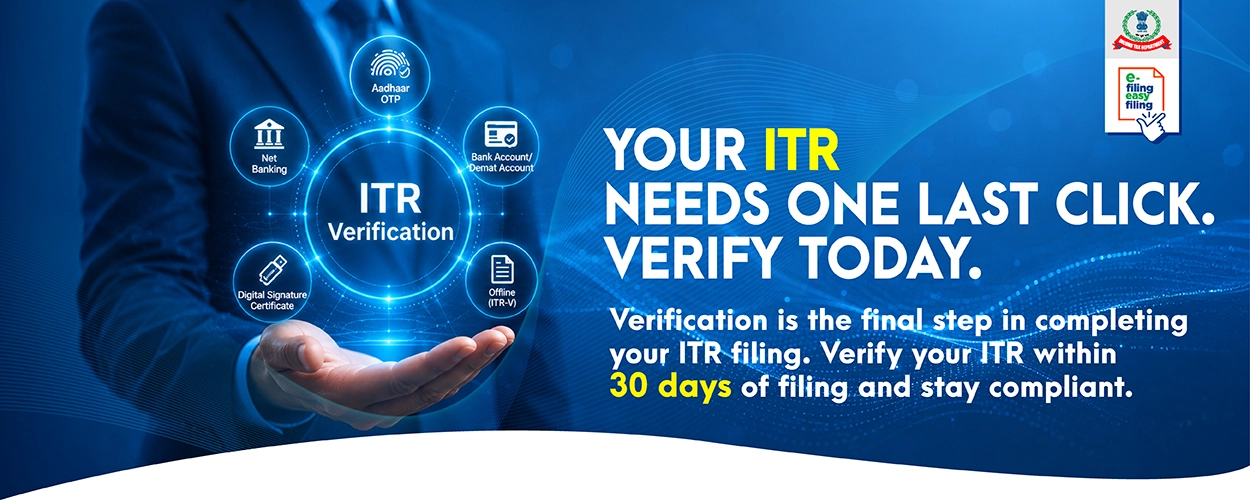  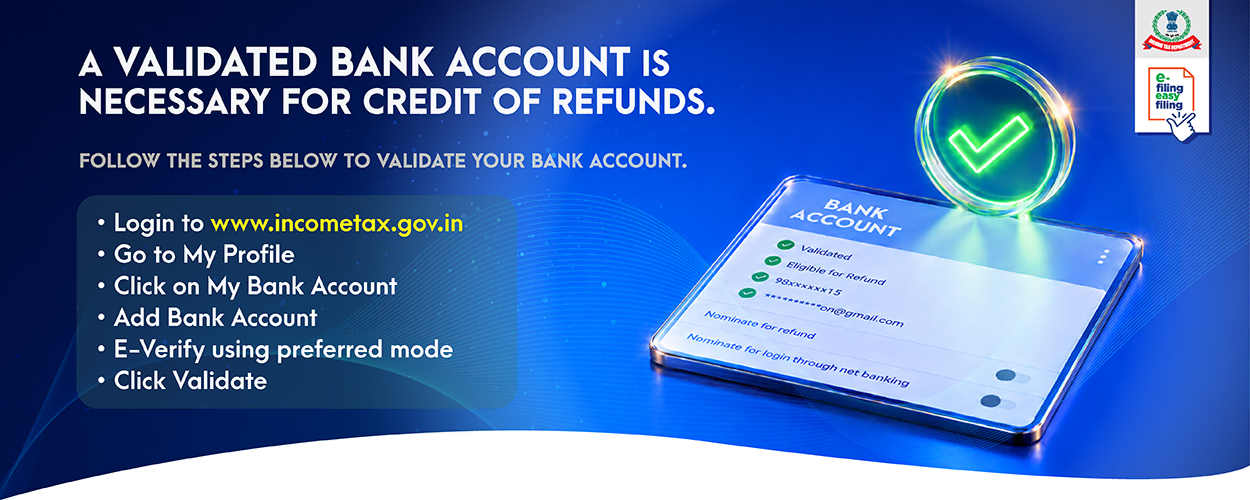 # What's New The Income Tax Department has enabled the **Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (FADS 2026)** on the e-Filing Portal. Under the scheme, eligible taxpayers can furnish the prescribed declaration form online through the e-Filing Portal. **Navigation Path: e-File → Income Tax Forms → File Income Tax Forms → Under Other Acts → Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (Form 1 of FADS 2026)** For detailed information and filing guidance, please refer to the FADS 2026 Documentation and User Guide available on the Income Tax Portal. # Latest Updates CBDT has notified the Income-tax (Eighth Amendment) Rules, 2026, vide Notification No. 139/2026 dated 30 October 2026, introducing Rule 189A and new Form 112A for intimating the merger of registered non-profit organisations having the same or similar objects under the Income-tax Act, 2025. File Form 10B/10BB by 21 October 2026 # Things to Know [\ \ **Revamped e-Filing Portal, Designed with taxpayers in mind**](https://youtu.be/rb36JDm8BbY) # Our Success Enablers The new and intuitive official website of Income Tax Department which deals with e-Filing of returns/forms and other related functionalities.
- incometax.gov.in › iec › foportal › latest-newsहिं
News & e-Campaigns - Income Tax Department
[](https://www.incometax.gov.in/iec/foportal/latest-news) # [](https://www.incometax.gov.in/iec/foportal/) News & e-Campaigns | Income Tax Department e-Filing of Income Tax Return or Forms and other value added services & Intimation, Rectification, Refund and other Income Tax Processing Related Queries 1800 103 0025 (or) 1800 419 0025 +91-80-46122000 +91-80-61464700 08:00 hrs - 20:00 hrs (Monday to Friday) +91-20-27218080 07:00 hrs - 23:00 hrs 1800 103 4215 09:30 hrs - 18:00 hrs (Monday to Friday) Select your language Englishहिंदी [](https://www.incometax.gov.in/iec/foportal/latest-news#/) [](https://www.incometax.gov.in/iec/foportal/latest-news#/) test 2. News & e-Campaigns ## News & e-Campaigns Year 202620252024202320222021202020192018201720162015201420132012 . 06-Nov-2026 [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-11/Notification-No-141-2026.pdf#) 03-Nov-2026 CBDT has notified the Income-tax (Eighth Amendment) Rules, 2026, vide Notification No. 139/2026 dated 30 October 2026, introducing Rule 189A and new Form 112A for intimating the merger of registered non-profit organisations having the same or similar objects under the Income-tax Act, 2025. [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-10/Notification-No-139-2026.pdf#) 27-Oct-2026 CBDT has proposed the Income-tax (Seventh Amendment) Rules, 2026, introducing Rule 281A and new Form 173A for furnishing information to claim exemption on interest income and capital gains from Government securities under Schedule IV of the Income-tax Act, 2025. [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-10/Notification-no-137-2026.pdf#) 12-Oct-2026 [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-10/Notification-133-2026.pdf#) 12-Oct-2026 CBDT has issued Notification No. 134/2026 dated 8 October 2026, notifying the Income-tax (Sixth Amendment) Rules, 2026, which introduce a revised Form 161 for filing applications for waiver of penalty under section 440(2) of the Income-tax Act, 2025. [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-10/Notification-no-134-2026.pdf#) 29-Sep-2026 As per Circular No.07/2026 dated 28th September,2026, the due dates for ITR and Audit Report are extended as below: Due date for filing of Income Tax Returns for AY 2026-27 is extended in the cases of persons mentioned at Sl.No.2 in the Table below Explanation2 to Sub-section (1) of Section 139 of Income Tax Act 1961 from 31st October 2026 to 21st November 2026" Accordingly, the Audit Reports for AY 2026-27 is extended in the cases of persons mentioned at Sl.No.2 in the Table below Explanation2 to Sub-section (1) of Section 139 of Income Tax Act 1961 from 30th September 2026 to 21st October, 2026. [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-09/Circular-7-2026.pdf#) 24-Sep-2026 CBDT has issued Notification No. 121/2026 extends TDS reporting requirements for non-resident property transactions and updates Forms 132 & 141. [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-09/Notification-no-121-2026.pdf#) 24-Sep-2026 [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-09/Notification-no-120-2026.pdf#) 21-Sep-2026 CBDT has issued Notification No. 3 of 2026 notifying the Procedure for registration of reporting person/entity and submission of Form No. 98 as per rule 160 of the Income-tax Rules, 2026. [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-09/Notification-3-of-2026.pdf#) 01-Sep-2026 114/2026 [F. 370142/18/2026-TPL], notifying the rules and prescribed forms under the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026. [Click here](https://www.incometax.gov.in/iec/foportal/sites/default/files/2026-08/Notification%20114.pdf#) Follow us on [](https://www.youtube.com/channel/UC-le1Uh6DI1oHjVxKck6Hpw)[](https://twitter.com/incometaxindia)[](https://www.facebook.com/Incometaxindia/)[](https://www.whatsapp.com/Incometaxindia/)[](https://www.instagram.com/incometaxindia.official?igshid=1npzoca4rcy57) Last reviewed and updated on : 07-Nov-2026 Copyright @ Income Tax Department, Ministry of Finance, Government of India. [](https://www.india.gov.in/) A2A
- facebook.com › incometaxindiaofficial › posts › 31st-august-2026-is-the-due-date-for-filing-itrs-for-ay-202627-for-taxpayers-witEN
31st August 2026 is the due date for filing ITRs for AY 2026–27 ...
31st August 2026 is the due date for filing ITRs for AY 2026–27 for taxpayers with business or professional income who are not subject to audit.
- incometaxindia.gov.in › income-tax-forms-2026हिं
Income Tax Forms 2026 | Download ITR, PAN & TDS Forms
Close Close Income Tax Forms, 2026 [Reckoner](https://www.incometaxindia.gov.in/reckoner) [Transfer Pricing](https://www.incometaxindia.gov.in/transfer-pricing) # Income Tax Forms, 2026 ## Search Searchinfo icon Enter atleast 3 characters. e.g., tax or TDS SearchReset Last Updated:September 15th, 2026 #### Instructions and Utility for Fillable Forms Please download [setup](https://incometaxindia.gov.in/Installer/setup.exe) file, extract on your system and double click on the extracted exe file, it will install fillable file opener on your system. After downloading the form click on it and it will open in form opener utility माह के लिए उन लेन-देनों के संबंध में किसी शेयर बाजार (स्टाक एक्सचेंज) द्वारा प्रस्तुत किया जाने वाला मासिक विवरण जिनमें सिस्टम में पंजीकरण के बाद ग्राहक कोड संशोधित किए गए हैं शून्य-कूपन बंधपत्र जारी करने वाली संस्था के लिए नियम 7 के अधीन लेखाकार का प्रमाणपत्र फार्म संख्या.: 6 धारा 44 के अधीन कुछ प्रारंभिक व्ययों या धारा 51 के अधीन कुछ खनिजों की संभावना के लिए व्यय की कटौती का दावा करने हेतु लेखापरीक्षा रिपोर्ट धारा 45(3)(ग) के अधीन वैज्ञानिक अनुसंधान कार्यक्रम के अनुमोदन के पश्चात् विहित प्राधिकारी द्वारा प्रायोजक पर अधिकार क्षेत्र रखने वाले मुख्य आयकर आयुक्त को प्रस्तुत की जाने वाली रिपोर्ट 1 - 10 of 193 itemsLoaded in : 0.31 seconds Drop file here orChoose File Drop file here orChoose File Compare sections first to enable export Kar SaathiAsk Me
- timesofindia.indiatimes.com › business › india-business › itr-deadline-on-july-31-2026-top-things-nris-should-keep-in-mind-when-filing-tax-returnEN
ITR deadline on July 31, 2026: Top things NRIs should keep in ...
ITR filing FY 2025-26: July 31, 2026 is the deadline to file income tax returns for salaried taxpayers and pensioners.
- eportal.incometax.gov.inEN
e-Filing Home Page, Income Tax Department, Government of ...
e-Filing Home Page, Income Tax Department, Government of India LOADING. To access this site, please enable JavaScript in your browser settings
- instagram.com › reel › DYWdbK0B8rnEN
ITR Filing for AY 2026-27 is Now LIVE! The Income Tax ...
The Income Tax Department has officially enabled online filing and Excel utilities for ITR-1 and ITR-4 on the e-Filing portal. Taxpayers ...
- reddit.com › r › IndiaTax › commentsEN
FY2025-26 Tax: when will the AY2026-27 efiling option will be ...
The ITR forms are now uploaded; however, the utility for filing returns will become operational approximately in the last week of this month ...
- incometax.gov.in › iec › foportal › helpEN
Salaried Individuals for AY 2026-27 - Income Tax Department
# [](https://www.incometax.gov.in/iec/foportal/) Salaried Individuals for AY 2026-27 | Income Tax Department ## Returns and Forms Applicable for Salaried Individuals for AY 2026-27 **Disclaimer:** The content on this page is only to give an overview and general guidance and is not exhaustive. For complete details and guidelines please refer to the Income Tax Act, 1961 Forms, Rules and Notifications. ## Forms Applicable (As per Income Tax Act,1961): | | | |-|-| | **5. Form 26 AS** | **AIS (Annual information Statement)** | | **Provided by:**<br>Income Tax Department (It is available on e-Filing Portal:<br>Login > e-File > Income Tax Return > View Form 26AS) | **Provided by:**<br>Income Tax Department (It can be accessed after logging on to Income Tax e-Filing portal)<br>Login to e-filing portal > AIS | | **Details provided in the form:**<br>Tax Deducted / Collected at Source. | **Details provided in the form:**<br>- Tax Deducted / Collected at Source<br>- SFT Information<br>- Payment of taxes<br>- Demand / Refund<br>Other information (like Pending/Completed proceedings, GST Information, Information received from foreign government etc.) | | | | |-|-| | **7. Form 15H - Declaration to be made by a resident individual (who is 60 years age or more) claiming certain receipts without deduction of tax** | | **Submitted by** | **Details provided in the form** | | A Resident Individual, 60 years or more to Bank for not deducting TDS on Interest Income | Estimated Income for the FY | #### Tax Slabs for AY 2026-27*** **New Tax Regime Vs Old Tax Regime:** The Finance Act 2023 has amended the provisions of Section 115BAC w.e.f AY 2024-25 to make new tax regime the default tax regime for the assessee being an Individual, HUF, AOP (not being co-operative societies), BOI and or Artificial Juridical Person. However, the eligible taxpayers have the option to opt out of default tax regime and choose to be taxed under old tax regime. The old tax regime refers to the system of income tax calculation and slabs that existed before the introduction of the new tax regime. In the old tax regime, taxpayers have the option to claim various tax deductions and exemptions. However, in default tax regime, tax rates are lower with very few deductions compared to old tax regime. **Non-business case:** In "Non-business cases", option to change the default tax regime can be exercised every year directly in the ITR and such ITR is required to be filed on or before the due date specified under section 139(1)of the Income Tax Act,1961. **Business case:** In case of eligible taxpayers having income from business and profession, if assessee wants to opt out of default tax regime, (New Tax regime),they have to furnish Form-10-IEA on or before the due date u/s 139(1) of the Income Tax Act,1961 for furnishing the return of income. Also, for the purpose of withdrawal of such option i.e. re-entering into default tax regime (New Tax regime) shall also be done by way of furnishing Form No.10-IEA on or before the due date specified u/s 139(1)of the Income Tax Act,1961 for furnishing return of income. However, option to withdraw from the old tax regime and re-enter into default tax regime (New Tax regime) ,is available only in subsequent AY and is available only once in lifetime for eligible taxpayers having income from business and profession. 1. Tax rates for Individual (resident or non-resident) less than 60 years of age anytime during the previous year are as below: | | | | | |-|-|-|-| | **Old Tax Regime** | **New Tax Regime u/s 115BAC of Income Tax Act,1961** | | **Income Tax Slab** | **Income Tax Rate** | **Income Tax Slab** | **Income Tax Rate** | | Up to ₹ 2,50,000 | Nil | Up to ₹ 4,00,000 | Nil | | ₹ 2,50,001 –<br>₹ 5,00,000 | 5% above ₹ 2,50,000 | ₹ 4,00,001 –<br>₹ 8,00,000 | 5% above ₹ 4,00,000 | | ₹ 5,00,001 –<br>₹ 10,00,000 | ₹ 12,500 + 20% above<br>₹ 5,00,000 | ₹ 8,00,001 –<br>₹ 12,00,000 | ₹ 20,000 + 10% above ₹ 8,00,000 | | Above<br>₹ 10,00,000 | ₹ 1,12,500 + 30% above<br>₹ 10,00,000 | ₹ 12,00,001 – ₹ 16,00,000 | ₹ 60,000 + 15% above ₹ 12,00,000 | | | ₹ 16,00,001 - ₹ 20,00,000 | ₹ 1,20,000 + 20% above ₹ 16,00,000 | | | ₹ 20,00,001 - ₹ 24,00,000 | ₹ 2,00,000 + 25% above ₹ 20,00,000 | | | Above ₹ 24,00,000 | ₹ 3,00,000 + 30% above ₹ 24,00,000 | 2. Tax rates for Individual (resident or non-resident), 60 years or more but less than 80 years of age anytime during the previous year are as under: | | | | | |-|-|-|-| | **Old Tax Regime** | **New Tax Regime u/s 115BAC of Income Tax Act,1961** | | **Income Tax Slab** | **Income Tax Rate** | **Income Tax Slab** | **Income Tax Rate** | | Up to <br>₹ 3,00,000 | Nil | Up to <br>₹ 4,00,000 | Nil | | ₹ 3,00,001 – <br>₹ 5,00,000 | 5% above ₹ 3,00,000 | ₹ 4,00,001 –<br>₹ 8,00,000 | 5% above ₹ 4,00,000 | | ₹ 5,00,001 – <br>₹ 10,00,000 | ₹ 10,000 + 20% above ₹ 5,00,000 | ₹ 8,00,001 –<br>₹ 12,00,000 | ₹ 20,000 + 10% above <br>₹ 8,00,000 | | Above <br>₹ 10,00,000 | ₹ 1,10,000 + 30% above ₹ 10,00,000 | ₹ 12,00,001 –<br>₹ 16,00,000 | ₹ 60,000 + 15% above<br>₹ 12,00,000 | | | ₹ 16,00,001 –<br>₹ 20,00,000 | ₹ 1,20,000 + 20% above<br>₹ 16,00,000 | | | ₹ 20,00,001 –<br>₹ 24,00,000 | ₹ 2,00,000 + 25% above<br>₹ 20,00,000 | | | Above<br>₹ 24,00,000 | ₹ 3,00,000 + 30% above<br>₹ 24,00,000 | | | | | | |-|-|-|-| | | | | | --- | --- | | **Old Tax Regime** | **New Tax Regime u/s 115BAC of Income Tax Act,1961** | | | | | | |-|-|-|-| | **Income Tax Slab** | **Income Tax Rate** | **Income Tax Slab** | **Income Tax Rate** | | Up to<br>₹ 5,00,000 | Nil | Up to ₹ 4,00,000 | Nil | | ₹ 5,00,001 –<br>₹ 10,00,000** | 20% above ₹ 5,00,000 | ₹ 4,00,001 – <br>₹ 8,00,000** | 5% above <br>₹ 4,00,000 | | above ₹ 10,00,000 | ₹ 1,00,000 + 30% above<br>₹ 10,00,000 | ₹ 8,00,001 – <br>₹ 12,00,000 | ₹ 20,000 + 10% above<br>₹ 8,00,000 | | | | ₹ 12,00,001 – <br>₹ 16,00,000 | ₹ 60,000 + 15% above <br>₹ 12,00,000 | | | | ₹ 16,00,001 – <br> ₹ 20,00,000 | ₹ 1,20,000 + 20% above <br> ₹ 16,00,000 | | | | ₹ 20,00,001 –<br>₹ 24,00,000 | ₹ 2,00,000 + 25% above <br> ₹ 20,00,000 | | | | Above<br> ₹ 24,00,000 | ₹ 3,00,000 + 30% above<br> ₹ 24,00,000 | | #### Applicable Surcharge Rates: | | | | |-|-|-| | **Net Income Range** | **Marginal Relief** | | **Exceeds (** ₹ **)** | **Does not exceed (** ₹ **)** | | 50 Lakhs | 1 Crore | Amount payable as income tax and surcharge shall not exceed the total amount payable as income tax on total income of ₹ 50 Lakhs by more than the amount of income that exceeds ₹ 50 Lakhs | | 1 Crore | 2 Crores | Amount payable as income tax and surcharge shall not exceed the total amount payable as income tax on total income of ₹ 1 crore by more than the amount of income that exceeds ₹ 1 crore | | 2 Crores | 5 Crores | Amount payable as income tax and surcharge shall not exceed the total amount payable as income tax on total income of ₹ 2 crores by more than the amount of income that exceeds ₹ 2 crores | | 5 Crores | - | Amount payable as income tax and surcharge shall not exceed the total amount payable as income tax on total income of ₹ 5 crores by more than the amount of income that exceeds ₹ 5 crores. |