Search results for how to income tax e-filing 2026 explained 2026 in India 2026
- incometax.gov.in › iec › foportalEN
Income Tax Department: Home
[](https://www.incometax.gov.in/iec/foportal/) # [](https://www.incometax.gov.in/iec/foportal/) Home | Income Tax Department  1. Form 3 under the “Foreign Assets of Small Taxpayers Disclosure Scheme” is now available for online filing 2. Due dates for filing of Income Tax Returns and Audit Reports for AY 2026-27 are extended in the cases of persons mentioned at Sl.No.2 in the Table below Explanation2 to Sub-section (1) of Section 139 of Income Tax Act 1961 vide Circular No.07/2026 dated 28th September,2026. 3. Form 1 under the “Foreign Assets of Small Taxpayers Disclosure Scheme” is now available for filing. 4. ITR-1, ITR-2, ITR-3, ITR-4, ITR-5, ITR-6 and ITR-7 for AY 2026-27 are available for filing through both online and offline utilities. 5. Filing of TDS/TCS Correction Statements pertaining to Tax Year 2026-27 has been enabled. 6. DFC may be contacted through the e-mail id: [taxdemand@cpc.incometax.gov.in](mailto:taxdemand@cpc.incometax.gov.in) or on the toll-free number - 1800 309 0131 or chargeable no. 0821-6671200. 7. Excel utilities for filing Updated return for ITR-1 to 7 for AY 2022-23 as per Finance Act, 2026 are available for filing ! 1. Form 3 under the “Foreign Assets of Small Taxpayers Disclosure Scheme” is now available for online filing 2. Due dates for filing of Income Tax Returns and Audit Reports for AY 2026-27 are extended in the cases of persons mentioned at Sl.No.2 in the Table below Explanation2 to Sub-section (1) of Section 139 of Income Tax Act 1961 vide Circular No.07/2026 dated 28th September,2026. 3. Form 1 under the “Foreign Assets of Small Taxpayers Disclosure Scheme” is now available for filing. 4. ITR-1, ITR-2, ITR-3, ITR-4, ITR-5, ITR-6 and ITR-7 for AY 2026-27 are available for filing through both online and offline utilities. 5. Filing of TDS/TCS Correction Statements pertaining to Tax Year 2026-27 has been enabled. 6. DFC may be contacted through the e-mail id: [taxdemand@cpc.incometax.gov.in](mailto:taxdemand@cpc.incometax.gov.in) or on the toll-free number - 1800 309 0131 or chargeable no. 0821-6671200. 7. Excel utilities for filing Updated return for ITR-1 to 7 for AY 2022-23 as per Finance Act, 2026 are available for filing ! ❚❚ 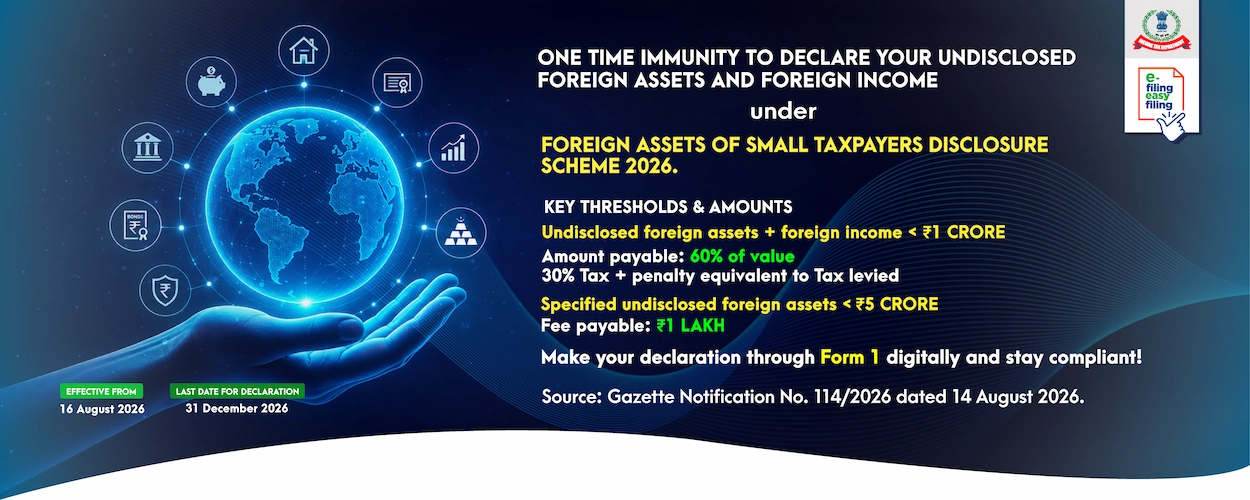    # What's New The Income Tax Department has enabled the **Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (FADS 2026)** on the e-Filing Portal. Under the scheme, eligible taxpayers can furnish the prescribed declaration form online through the e-Filing Portal. **Navigation Path: e-File → Income Tax Forms → File Income Tax Forms → Under Other Acts → Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (Form 1 of FADS 2026)** For detailed information and filing guidance, please refer to the FADS 2026 Documentation and User Guide available on the Income Tax Portal. # Latest Updates E-Mail E-Mail File Form 10B/10BB by 21 October 2026 # Things to Know [\ \ **How to file ITR in offline mode**](https://youtu.be/naIvEN0I1WY) [\ \ **Revamped e-Filing Portal, Designed with taxpayers in mind**](https://youtu.be/rb36JDm8BbY) # Our Success Enablers The new and intuitive official website of Income Tax Department which deals with e-Filing of returns/forms and other related functionalities.
- incometax.gov.in › iec › foportal › helpEN
Income Tax Returns
# Income Tax Returns ## [Income Tax Returns FAQs](https://www.incometax.gov.in/iec/foportal/help/all-topics/e-filing-services/%20income%20tax%20returns-faq) ### 3. Will taxpayers be required to file two returns (for AY 2026 -27 as well as TY 2026 -27) during the transition year (FY 2026 -27)? No. ### 4. Under which Act will the ITR for income earned during FY 2025 -26 be filed? Even though the filing will typically occur after 1st April, 2026 (i.e., after the new Act has come into force), the return relates to a tax year beginning before 1st April, 2026 and is therefore governed entirely by the old Act. ### 5. Which ITR form should be used for AY 2026 -27? For AY 2026 -27, the ITR forms (ITR -1, ITR -2, ITR -3, ITR -4, ITR -5, ITR -6, ITR -7) applicable under the Income Tax Act, 1961 will soon be notified. ### 8. Can a taxpayer file an updated return (ITR -U) for AY 2026 -27 under the old Act after the new Act comes into force? The updated return for AY 2026 -27 under Section 139(8A) of the old Act can be filed within the time period prescribed therein, even after the new Act has come into force. He can file an updated return (ITR -U) for AY 2026 -27 under the old Act, subject to the time limits and additional tax requirem ents prescribed in Section 139(8A) of the old Act. ### 16. Are AY 2026 -27 and Tax Year 2026 -27 the same? (i) For AY 2026 -27 (income of FY 2025 -26): File the return using old ITR forms on the e -filing portal, selecting AY 2026 -27. (ii) For Tax Year 2026 -27 (income of FY 2026 -27): This return is not due until July 2027. However, the taxpayer should keep track of income, TDS, and advance tax payments under the new Act framework from April 2026 onwards. ### 24. The tax audit report for FY 2025 -26 will be filed after 1st April, 2026. Which Act will govern the filing of the tax audit report for FY 2025 -26 (AY2026 -27)? 2026 . ### 27. How should taxpayers keep records for the transition year to ensure smooth filing under both Acts? (iii) Reconcile Form 26AS / Annual Tax Statement for each year separately; (iv) Keep a section -mapping reference handy (old Act section to new Act section) for accurate reporting; [](https://www.youtube.com/channel/UC-le1Uh6DI1oHjVxKck6Hpw)[](https://twitter.com/incometaxindia)[](https://www.facebook.com/Incometaxindia/)[](https://www.whatsapp.com/Incometaxindia/)[](https://www.instagram.com/incometaxindia.official?igshid=1npzoca4rcy57) Last reviewed and updated on : 06-Nov-2026
- incometax.gov.in › iec › foportal › helpEN
Salaried Individuals for AY 2026-27 - Income Tax Department
# [](https://www.incometax.gov.in/iec/foportal/) Salaried Individuals for AY 2026-27 | Income Tax Department ## Returns and Forms Applicable for Salaried Individuals for AY 2026-27 **Disclaimer:** The content on this page is only to give an overview and general guidance and is not exhaustive. For complete details and guidelines please refer to the Income Tax Act, 1961 Forms, Rules and Notifications. | | | |-|-| | **2. ITR-2 - Applicable for Individual (Not eligible for ITR 1) and HUF** | | This return is applicable for Individual and Hindu Undivided Family (HUF) | | | | | | --- | --- | | Having Income under any head other than Profits and Gains of Business or Profession. | Who is not eligible to file ITR-1 | | | | | |-|-| | **3. ITR-3- Applicable for Individual and HUF** | | This return is applicable for Individual and Hindu Undivided Family (HUF) | | | | | | --- | --- | | Having Income under the heads Salary/Pension, House Property, Profits or Gains of Business or Profession, Capital Gains or Income from Other Sources. | Who is not eligible to file ITR-1, ITR-2 or ITR-4 | | | | | | | | |-|-|-|-|-| | **4. ITR-4 (SUGAM) – Applicable for Individual, HUF and Firm (other than LLP)** | | This return is applicable for an Individual or Hindu Undivided Family (HUF), who is Resident other than Not Ordinarily Resident or a Firm (other than LLP) which is a Resident having Total Income under Business or Profession which is computed on a presumptive basis (u/s 44AD / 44ADA / 44AE of Income Tax Act,1961) and income from any of the following sources: | | | | | | | | | --- | --- | --- | --- | --- | | Salary / Pension | One House Property | Other sources (Interest, Family Pension, Dividend etc.) | Agricultural Income up to ₹ 5,000 | Capital Gain income u/s 112 A (Income Tax Act,1961) up to ₹ 1,25,000 | | | **Note 1:**<br>ITR-4 cannot be used by a person who:<br>01. is a Director in a company<br>02. has short term capital gains <br>03. has Long-term capital gain u/s 112A of Income Tax Act,1961 exceeding ₹1,25,000<br>04. has held any unlisted equity shares at any time during the previous year <br>05. has any asset (including financial interest in any entity) located outside India<br>06. has signing authority in any account located outside India <br>07. has income from any source outside India <br>08. is a person in whose case payment or deduction of tax has been deferred on ESOP<br>09. who has any brought forward loss or loss to be carried forward under any head of income<br>10. has total income exceeding ₹50 lakhs (excluding LTCG u/s 112A upto ₹1,25,000)<br>**Note 2:**<br>ITR-4 (Sugam) is not mandatory. It is a simplified return form to be used by an Assessee, at his option, if he is eligible to declare Profits and Gains from Business or Profession on presumptive basis u/s 44AD, 44ADA or 44AE of Income Tax Act,1961. | ## Forms Applicable (As per Income Tax Act,1961): | | | |-|-| | **5. Form 26 AS** | **AIS (Annual information Statement)** | | **Provided by:**<br>Income Tax Department (It is available on e-Filing Portal:<br>Login > e-File > Income Tax Return > View Form 26AS) | **Provided by:**<br>Income Tax Department (It can be accessed after logging on to Income Tax e-Filing portal)<br>Login to e-filing portal > AIS | | **Details provided in the form:**<br>Tax Deducted / Collected at Source. | **Details provided in the form:**<br>- Tax Deducted / Collected at Source<br>- SFT Information<br>- Payment of taxes<br>- Demand / Refund<br>Other information (like Pending/Completed proceedings, GST Information, Information received from foreign government etc.) | #### Tax Slabs for AY 2026-27*** **New Tax Regime Vs Old Tax Regime:** The Finance Act 2023 has amended the provisions of Section 115BAC w.e.f AY 2024-25 to make new tax regime the default tax regime for the assessee being an Individual, HUF, AOP (not being co-operative societies), BOI and or Artificial Juridical Person. However, the eligible taxpayers have the option to opt out of default tax regime and choose to be taxed under old tax regime. The old tax regime refers to the system of income tax calculation and slabs that existed before the introduction of the new tax regime. In the old tax regime, taxpayers have the option to claim various tax deductions and exemptions. However, in default tax regime, tax rates are lower with very few deductions compared to old tax regime. **Non-business case:** In "Non-business cases", option to change the default tax regime can be exercised every year directly in the ITR and such ITR is required to be filed on or before the due date specified under section 139(1)of the Income Tax Act,1961. **Business case:** In case of eligible taxpayers having income from business and profession, if assessee wants to opt out of default tax regime, (New Tax regime),they have to furnish Form-10-IEA on or before the due date u/s 139(1) of the Income Tax Act,1961 for furnishing the return of income. Also, for the purpose of withdrawal of such option i.e. re-entering into default tax regime (New Tax regime) shall also be done by way of furnishing Form No.10-IEA on or before the due date specified u/s 139(1)of the Income Tax Act,1961 for furnishing return of income. However, option to withdraw from the old tax regime and re-enter into default tax regime (New Tax regime) ,is available only in subsequent AY and is available only once in lifetime for eligible taxpayers having income from business and profession. 1. Tax rates for Individual (resident or non-resident) less than 60 years of age anytime during the previous year are as below: | | | | | |-|-|-|-| | **Old Tax Regime** | **New Tax Regime u/s 115BAC of Income Tax Act,1961** | | **Income Tax Slab** | **Income Tax Rate** | **Income Tax Slab** | **Income Tax Rate** | | Up to ₹ 2,50,000 | Nil | Up to ₹ 4,00,000 | Nil | | ₹ 2,50,001 –<br>₹ 5,00,000 | 5% above ₹ 2,50,000 | ₹ 4,00,001 –<br>₹ 8,00,000 | 5% above ₹ 4,00,000 | | ₹ 5,00,001 –<br>₹ 10,00,000 | ₹ 12,500 + 20% above<br>₹ 5,00,000 | ₹ 8,00,001 –<br>₹ 12,00,000 | ₹ 20,000 + 10% above ₹ 8,00,000 | | Above<br>₹ 10,00,000 | ₹ 1,12,500 + 30% above<br>₹ 10,00,000 | ₹ 12,00,001 – ₹ 16,00,000 | ₹ 60,000 + 15% above ₹ 12,00,000 | | | ₹ 16,00,001 - ₹ 20,00,000 | ₹ 1,20,000 + 20% above ₹ 16,00,000 | | | ₹ 20,00,001 - ₹ 24,00,000 | ₹ 2,00,000 + 25% above ₹ 20,00,000 | | | Above ₹ 24,00,000 | ₹ 3,00,000 + 30% above ₹ 24,00,000 | 2. Tax rates for Individual (resident or non-resident), 60 years or more but less than 80 years of age anytime during the previous year are as under: | | | | | |-|-|-|-| | **Old Tax Regime** | **New Tax Regime u/s 115BAC of Income Tax Act,1961** | | **Income Tax Slab** | **Income Tax Rate** | **Income Tax Slab** | **Income Tax Rate** | | Up to <br>₹ 3,00,000 | Nil | Up to <br>₹ 4,00,000 | Nil | | ₹ 3,00,001 – <br>₹ 5,00,000 | 5% above ₹ 3,00,000 | ₹ 4,00,001 –<br>₹ 8,00,000 | 5% above ₹ 4,00,000 | | ₹ 5,00,001 – <br>₹ 10,00,000 | ₹ 10,000 + 20% above ₹ 5,00,000 | ₹ 8,00,001 –<br>₹ 12,00,000 | ₹ 20,000 + 10% above <br>₹ 8,00,000 | | Above <br>₹ 10,00,000 | ₹ 1,10,000 + 30% above ₹ 10,00,000 | ₹ 12,00,001 –<br>₹ 16,00,000 | ₹ 60,000 + 15% above<br>₹ 12,00,000 | | | ₹ 16,00,001 –<br>₹ 20,00,000 | ₹ 1,20,000 + 20% above<br>₹ 16,00,000 | | | ₹ 20,00,001 –<br>₹ 24,00,000 | ₹ 2,00,000 + 25% above<br>₹ 20,00,000 | | | Above<br>₹ 24,00,000 | ₹ 3,00,000 + 30% above<br>₹ 24,00,000 | | | | | | |-|-|-|-| | **Income Tax Slab** | **Income Tax Rate** | **Income Tax Slab** | **Income Tax Rate** | | Up to<br>₹ 5,00,000 | Nil | Up to ₹ 4,00,000 | Nil | | ₹ 5,00,001 –<br>₹ 10,00,000** | 20% above ₹ 5,00,000 | ₹ 4,00,001 – <br>₹ 8,00,000** | 5% above <br>₹ 4,00,000 | | above ₹ 10,00,000 | ₹ 1,00,000 + 30% above<br>₹ 10,00,000 | ₹ 8,00,001 – <br>₹ 12,00,000 | ₹ 20,000 + 10% above<br>₹ 8,00,000 | | | | ₹ 12,00,001 – <br>₹ 16,00,000 | ₹ 60,000 + 15% above <br>₹ 12,00,000 | | | | ₹ 16,00,001 – <br> ₹ 20,00,000 | ₹ 1,20,000 + 20% above <br> ₹ 16,00,000 | | | | ₹ 20,00,001 –<br>₹ 24,00,000 | ₹ 2,00,000 + 25% above <br> ₹ 20,00,000 | | | | Above<br> ₹ 24,00,000 | ₹ 3,00,000 + 30% above<br> ₹ 24,00,000 | |
- incometaxindia.gov.in › income-tax-rule-2026EN
Income Tax Rules 2026 | Latest Tax Updates
Close Menu - [Take Online Oath](https://www.incometaxindia.gov.in/take-online-oath)
- facebook.com › incometaxindiaofficial › posts › 31st-august-2026-is-the-due-date-for-filing-itrs-for-ay-202627-for-taxpayers-witEN
31st August 2026 is the due date for filing ITRs for AY 2026–27 ...
31st August 2026 is the due date for filing ITRs for AY 2026–27 for taxpayers with business or professional income who are not subject to audit.
- indiafirstlife.com › knowledge-center › tax-savings › how-to-file-itr-onlineEN
How to File ITR Online for AY 2026-27 (FY 2025-26)
Step 1: Register/Login on the Income Tax E-Filing Portal · Step 2: Select the Right ITR Form · Step 3: Provide Basic Information and Select Status · Step 4: Enter ...
- m.economictimes.com › wealth › tax › itr-filing-2026-step-by-step-guide-to-filing-itr-1-for-ay-2026-27-before-the-july-31-deadlineEN
ITR filing 2026: Step-by-step guide to filing ITR-1 for AY 2026 ...
Students, salaried individuals, and pensioners can file ITR-1 for AY 2026-2027. The deadline for filing this income tax return is July 31, 2026.
- instagram.com › reel › DYWdbK0B8rnEN
ITR Filing for AY 2026-27 is Now LIVE! The Income Tax ...
The Income Tax Department has officially enabled online filing and Excel utilities for ITR-1 and ITR-4 on the e-Filing portal. Taxpayers ...
- youtube.com › watchEN
ITR Filing 2026-27 in 4 Minutes New Income Tax e-Filing Portal
ITR 1 online 2026-27 bharna bahut aasan hai. Income Tax E filing ... India, New Income Tax Portal, e Filing Income Tax, ITR Return ...
- reddit.com › r › IndiaTax › commentsEN
FY2025-26 Tax: when will the AY2026-27 efiling option will be ...
The ITR forms are now uploaded; however, the utility for filing returns will become operational approximately in the last week of this month ...